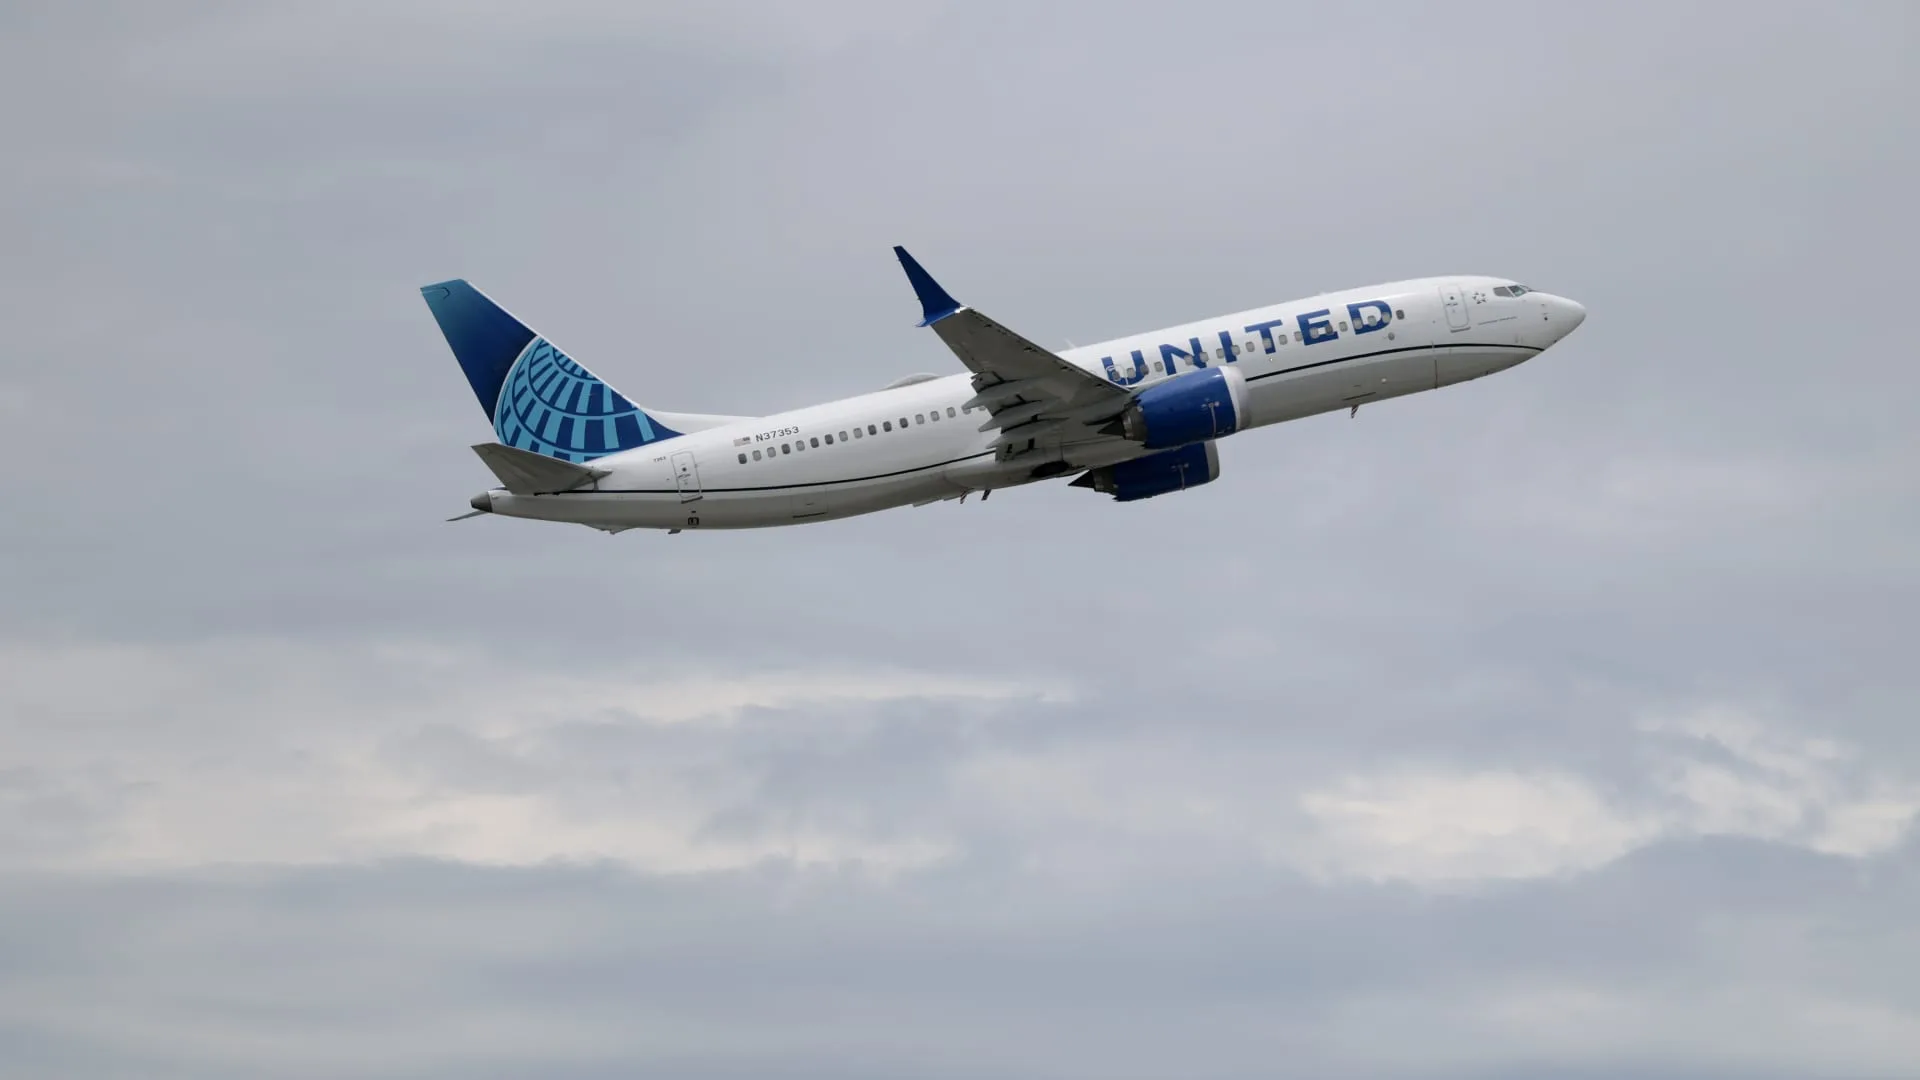
United Airlines reported second-quarter adjusted EPS above Street forecasts but said surging jet fuel costs could add roughly $6 billion to 2026 expenses, forcing updated guidance and possible capacity cuts.
United Airlines (UAL) said Wednesday that second-quarter results topped Wall Street estimates, yet sharply higher jet fuel costs remain the dominant risk to 2026 profits and capacity planning. The carrier raised its full-year adjusted earnings range but flagged roughly $6 billion of additional fuel expense versus its January outlook and trimmed third-quarter guidance versus analyst models.
Strong quarterly topline; fuel drags profitability
United reported adjusted earnings per share of $1.99 for the quarter ended June 30, beating the LSEG consensus of $1.88. Revenue for the quarter was $17.67 billion, slightly above the $17.61 billion analysts expected. On a GAAP basis, net income fell more than 17% to $805 million, or $2.46 a share; adjusted net income was $649 million, or $1.99 a share.
The airline said second-quarter fuel expense rose 84% year-over-year to $2.3 billion. Using fuel prices as of Tuesday, United estimated that higher jet fuel would add nearly $6 billion to its 2026 costs compared with expectations at the start of the year. That fuel estimate underpins the company’s updated guidance and capacity consideration.
Updated guidance and capacity notes
United forecast third-quarter adjusted EPS of $2.50 to $3.50, below analyst estimates of $3.60. For the full year, it raised its adjusted EPS outlook to a $9.00–$11.00 range (up from a previously stated $7–$11 range in April), noting the higher end reflects recent adjustments but remains sensitive to volatile fuel. The company said it expects to cover up to 90% of its higher fuel costs in the current quarter and all of the incremental fuel expense in the fourth quarter.
United also said it could further cut capacity plans this year if fuel prices remain elevated, signaling possible reductions in flying beyond the 3.5% capacity expansion reported for Q2.
Demand, ticket mix and unit revenue trends
Despite higher fares, United said customers continue to book travel. The carrier’s second-quarter revenue rose 16% year-over-year to $17.67 billion, driven in part by a 12.1% increase in total unit revenue — the highest unit-revenue growth since early 2023, according to FactSet. United reported rising revenue across premium, corporate and basic-economy fare classes, and unit revenue improved for both domestic and international itineraries.
Industry context and fuel volatility
Jet fuel is the largest operating cost for airlines after labor. Industry data cited by Airlines for America and Argus show jet fuel prices at major U.S. airports were up 34% in July through Tuesday amid episodic escalation and de-escalation of U.S.-Iran tensions. Rival Delta Air Lines (DAL) has also said it is passing more of those costs onto customers, and both carriers report resilient demand despite higher airfares.
What United said about fuel impact on EPS
United quantified the immediate earnings impact of recent fuel moves: since the start of July, the company said fuel price changes have reduced its third-quarter adjusted EPS outlook by $1.12 per share (based on fuel levels used in the company’s update).
Upcoming investor event
United executives will host an earnings call Thursday at 10:30 a.m. ET to discuss the results and the updated outlook.
Key Quotes
- United: higher fuel could add nearly $6 billion in expenses this year compared with start-of-year expectations. (Company statement)
- United: second-quarter fuel costs rose 84% from last year to $2.3 billion. (Company statement)
Bottom Line for Traders
United’s Q2 beat on adjusted EPS and revenue shows solid demand and stronger unit revenue, but the company’s profitability and capacity plans are now materially subject to volatile jet fuel prices. Traders should note the company’s updated third-quarter EPS range that falls short of consensus and its explicit $6 billion fuel headwind estimate as key drivers for near-term stock sensitivity. The market reaction will likely depend on how fuel prices evolve and on management’s commentary in the upcoming earnings call.
$UAL Live Price, Interactive Charts and Performance Graphs
Market data may be delayed. See StockMarketLoop’s financial disclaimer.